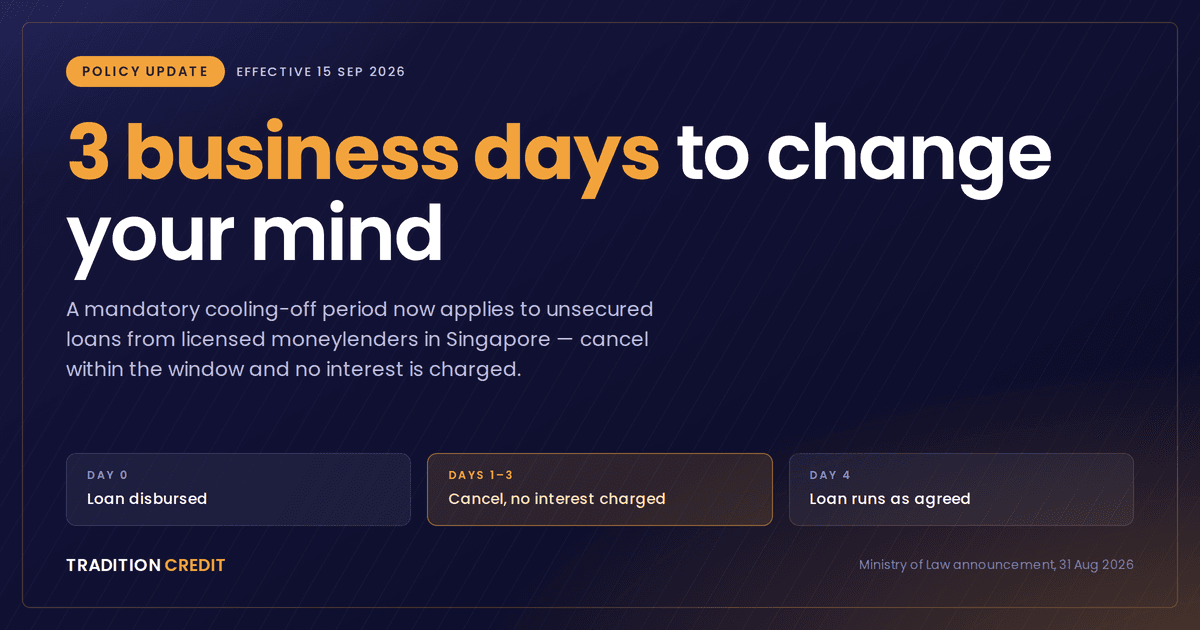
From today, 15 September 2026, anyone who takes an unsecured loan from a licensed moneylender in Singapore can walk away from it within three business days — and walk away without paying a single dollar of interest.
The Ministry of Law announced the new rule on 31 August 2026. It is a small change on paper and a significant one in practice, because it puts a pause between the moment a loan is approved and the moment a borrower is fully committed to it.
- You get three business days to cancel a new unsecured loan. Weekends and public holidays do not count.
- Cancel inside it and no interest is charged at all.
- The lender keeps at most S$50 on loans of S$5,000 or less, or 3.5% of principal on loans above S$5,000 — never more than the approval fee charged.
- Applies to every unsecured loan from a licensed moneylender except business loans.
What the Three Days Actually Cover
The cooling-off period runs for three business days. Saturdays, Sundays and Singapore public holidays do not count towards the three, so a weekend or a long weekend cannot quietly eat into your thinking time.
It applies to all unsecured loans from licensed moneylenders, except business loans. Personal loans, medical loans, wedding loans, payday loans — all covered. If you are borrowing to fund a company, the cooling-off period does not apply to that facility.
What Changes If You Cancel
Until now, a borrower who cancelled a loan was in an awkward position. The moneylender was entitled to keep the entire loan approval fee, plus any interest that had already accrued. Cancelling was rarely worth it.
Under the new framework, two things change during the cooling-off window:
- No interest is charged at all.
- The lender may keep only part of the loan approval fee — a capped amount meant to cover the overheads and due diligence involved in assessing your application, not the profit on the loan.
There will be no interest charged, and the total you repay cannot exceed the principal amount of the loan.
Ministry of Law, 31 August 2026
WAS 2 business days Until 14 Sep 2026 | NOW 3 business days From 15 Sep 2026 |
How Much of the Fee the Lender Can Keep
| Principal amount of the unsecured loan (other than a business loan) | Maximum the licensed moneylender may retain |
|---|---|
| S$5,000 or less | S$50, and never more than the loan approval fee charged |
| More than S$5,000 | 3.5% of the principal, and never more than the loan approval fee charged |
The cap is a ceiling, not an entitlement — if the approval fee charged was lower than the cap, the lender keeps the lower figure.
A Worked Example
Say you take a S$1,000 personal loan with a 10% loan approval fee, think it over, and cancel on day two.
| Cancelling a S$1,000 loan on day 2 | 10% approval fee | |
| Principal | S$1,000 | |
| Less loan approval fee, deducted upfront | − S$100 | |
| Cash that reaches your hands | S$900 | |
| Fee the lender may retain (principal ≤ S$5,000) | S$50 | |
| Interest charged | S$0 | |
| You repay | S$950 | |
| The same arithmetic scales up: on a S$10,000 loan, the retained portion is capped at 3.5%, or S$350. | ||
No interest. Nothing beyond the original S$1,000 principal. The same arithmetic scales up: on a S$10,000 loan, the retained portion is capped at 3.5%, or S$350.
What to Do If You Want to Cancel
- 1
Tell the lender inside the window — in writing if you can, so the date is on record. - 2
Return the principal you received, in full. - 3
Pay the retained portion of the approval fee, capped as set out above. - 4
Ask for written confirmation that the loan is settled and closed.
If the lender refuses
The cooling-off period applies by law. Nothing in a loan agreement can remove it. If a licensed moneylender will not honour it, the Registry of Moneylenders takes complaints directly.
- Solicit loans through text messages, phone calls or social media. An unsolicited “loan offer” in your inbox is not from a licensed lender.
- Grant a loan without meeting you in person at its approved place of business and verifying your identity face to face.
Licensed Lender, or Loan Shark?
✓ A licensed moneylender
| ✕ A loan shark
|
Every licensed moneylender in Singapore is listed on the Ministry of Law’s
Registry of Moneylenders
.
If a name is not on that list, do not borrow from it.
Why It Was Introduced
The Ministry of Law developed the framework in consultation with the Credit Association of Singapore, the professional body representing licensed moneylenders.
The reasoning is a balancing act, and the Ministry has been open about both sides of it. Credit decisions are sometimes made on impulse, and a borrower deserves a genuine chance to reconsider one. At the same time, a lender has already done real work — checking your income, running the due diligence, approving the file — by the time a loan is disbursed, and should not be left uncompensated for it.
Implementation was set for 15 September 2026 rather than immediately, giving licensed moneylenders time to adjust their processes and systems. The Registry of Moneylenders, which sits under the Ministry, is working with the industry to keep the rollout smooth.
The Other Change You May Have Missed
In April 2026, the Registry of Moneylenders updated its Professional Service Handbook for Licensed Moneylenders with a set of best practices lenders are encouraged to adopt:
- Reward good repayment behaviour — discounts or rebates on interest and fees for borrowers who pay on time or settle ahead of schedule.
- Offer digital tools — an online portal, for instance, so borrowers can track their own loan servicing and manage their finances.
- Step in early for borrowers in difficulty — restructuring repayments to suit the borrower’s actual financial situation, or referring them to a Social Service Agency.
These are encouragements rather than obligations, but they signal the direction the industry is being nudged in.
What This Means at Tradition Credit
We have been lending in Bedok since 1994, and this is the kind of rule we welcome. A borrower who has had three clear days to think it over is a borrower who repays comfortably — which is the only kind of loan worth writing.
If you take an unsecured personal loan with us from today onward, the three-business-day cooling-off period applies automatically. You do not need to ask for it, and nothing in your loan agreement can take it away. If you decide during that window that the loan is not right for you, tell us, and we will settle it under the terms above.
Questions about how this affects a loan you are considering? Call us on 6283 1323 or drop by the office — we would rather talk it through than have you sign something you are unsure about.
Common Questions
+
+
+
+
+
Source: Ministry of Law,
“Mandatory Cooling-off Period for Loans Taken from Licensed Moneylenders”
,
31 August 2026. This article is general information, not financial or legal advice. For the authoritative wording, refer to the Ministry’s release and the Moneylenders Act.